In this guide
The garage invoice and the insurer’s settlement statement answer different questions. The invoice records work and charges. The settlement statement explains the amount the insurer has admitted under the policy. When those totals differ, the first useful step is to request the calculation—not assume that a bill or claim must be wrong.
Put three documents side by side
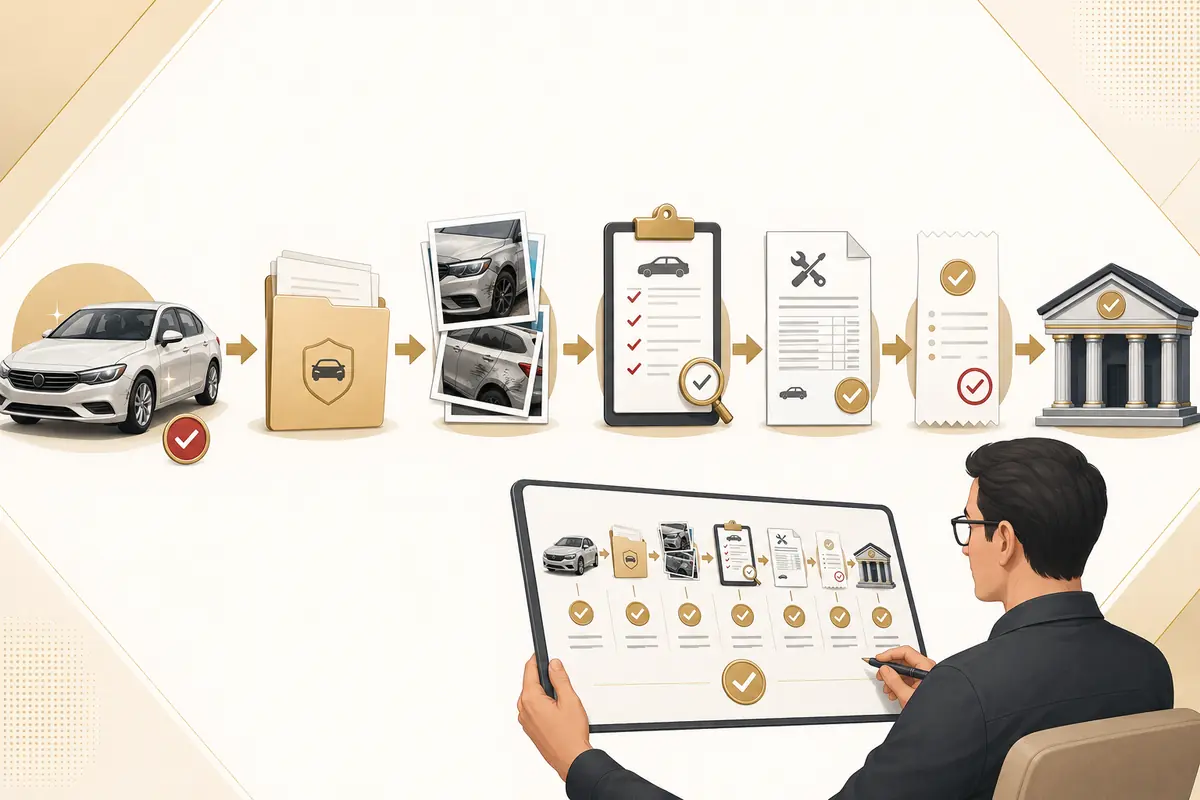
Keep the issued policy schedule and wording, the itemised repair invoice and the insurer’s settlement explanation together. Add the approved estimate, payment receipt and claim reference.
HDFC ERGO’s reimbursement guidance describes the customer paying the repair bill and then submitting the required records for assessment of eligible costs. ICICI Lombard’s motor-claim information also identifies the invoice and payment receipt as additional reimbursement records. Neither process means that every invoiced rupee is automatically payable.
Ask the insurer which version of the estimate it assessed. If a later repair item was added, check whether the insurer received the additional evidence and approval request.
Identify the reason for each difference
A deduction should have an explanation connected to the policy or the assessment. Request separate figures rather than one unexplained “customer share.”
Possible headings include the deductible, depreciation on eligible parts, items outside the admitted loss and charges the insurer has not accepted. These are questions to investigate, not a prediction of what will be deducted from your claim. Avoid copying someone else’s settlement percentages into your own calculation.
Zero depreciation is not the same as zero payment
An applicable zero-depreciation add-on can change how depreciation is treated, but it does not make every expense payable. ICICI Lombard’s own zero-depreciation guidance notes that the compulsory deductible still applies and that cover conditions must be read.
Ask whether the add-on appears on your issued schedule and whether its conditions apply to this event. The workshop cannot create an add-on after damage has occurred or override an insurer’s policy decision.
Separate billing questions from coverage questions
The workshop can explain the parts supplied, labour charged and work recorded. The insurer should explain admissibility and policy deductions. Send each query to the party that can answer it, keeping copies of the correspondence.
For example, an unclear part description belongs first with the repairer; a deduction attributed to a policy condition needs the insurer’s explanation. If the accounts do not reconcile, ask for the relevant supporting document rather than changing the invoice to match a desired claim result.
Keep a calm, traceable query
Quote the claim number, identify the disputed line and attach the relevant record through the insurer’s official channel. Ask for the reason and calculation in writing. If unresolved, use the insurer’s published grievance process. This guide does not prescribe a complaint deadline or guarantee a revised payment.
Cashless authorization, claim admissibility and final approval depend on the customer’s policy terms, insurer approval, survey findings and applicable network/cashless arrangements.
CarTech Hub – Multi-Brand Car Workshop in Guwahati publishes claim assistance information, insurer pages and accident repair guidance. Contact staff about workshop records; the insurer retains responsibility for its settlement decision.
Reference: HDFC ERGO reimbursement process.