In this guide
Guwahati waterlogging can leave an owner uncertain whether a Seltos should be restarted after standing in water. Imagine finding moisture inside the cabin and an abnormal warning after the water recedes. CarTech Hub can coordinate a safe assessment and help organise a United India insurance enquiry. The depth, exposure and actions taken matter. Flood-related damage, mechanical consequences and routine deterioration are separate assessment questions, so this example does not promise engine coverage or an approved cashless repair.
Avoid restarting an exposed vehicle
Keep away from unsafe water and obtain appropriate recovery guidance rather than attempting to drive out. Do not restart a suspected water-affected engine to check whether it will run. Photograph the vehicle, location, visible water level or residue and cabin condition only when safe. Note exposure times as accurately as possible and retain recovery information. Contact United India through the official service shown on the policy promptly, explaining any starting attempts truthfully and asking how inspection should be arranged before cleaning or repair alters the evidence.
Assess the Seltos actually involved
Petrol, turbo-petrol and diesel Seltos versions differ, and generations have different electrical and intake arrangements. Confirm VIN, year and powertrain before estimating. Depending on exposure, assessment may concern intake evidence, engine condition, wiring, low-mounted components, carpet and interior fittings. A moisture stain does not prove that every electronic module requires replacement. Restraints, complex electronics or internal engine work need confirmed qualified scope or specialist referral. Manufacturer warranty or campaign questions should go through the appropriate Kia route; CarTech Hub is an independent workshop.
Review United India's cover before selecting a repair route
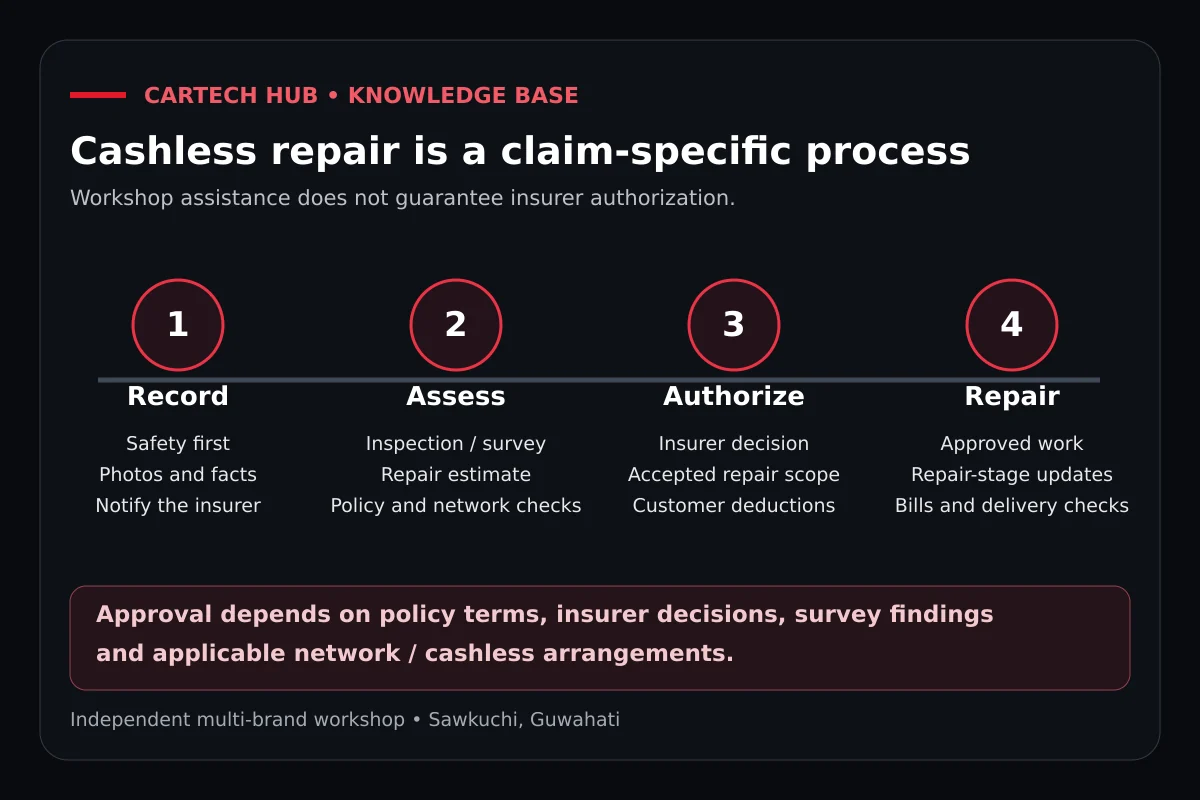
Ask United India to verify the active policy sections and any relevant endorsements. The insurer's private-car documents distinguish own-damage policies from liability-only protection; the precise issued wording governs this loss. This article does not assume an engine-protection add-on, a cashless network acceptance or an exemption from exclusions. Request the correct claim-intimation and assessment instructions from the current servicing channel. CarTech Hub can help compile evidence and an estimate, while the insurer retains the decisions on admissibility, survey findings and final payable scope.
Collect documents without erasing evidence
Prepare the policy schedule and wording, RC, relevant driving licence, completed claim form or instructed declaration, and clear photographs. State whether the car was parked or being driven, and who used it if relevant. Keep recovery records and the workshop estimate. United India may ask for additional incident, identity, ownership or payment evidence. A police report or FIR is provided where applicable or requested; waterlogging should not be described as requiring one in every case. Record earlier leaks or electrical problems separately from the new exposure.
Obtain inspection instructions before opening affected systems
The required insurer inspection or survey should precede insured dismantling, cleaning that changes evidence or repairs, unless United India authorises another sequence. Ask how urgent measures to limit further loss should be documented.
Itemise the exposure-related findings
The estimate should separate confirmed damage, further diagnosis, interior restoration and proposed parts. If authorised access uncovers more affected components, submit a supplementary estimate with photographs and test findings for approval. Do not discard damaged items until retention instructions are clear, or substitute a blanket engine-overhaul request for a supported diagnosis.
Discuss exclusions and the customer share plainly
Eligible own-damage cover is required for the Seltos's own loss; third-party-only insurance does not pay to restore this vehicle. Ordinary deterioration and unrelated maintenance are not automatically flood damage. Cashless authorization, admissibility and final approval depend on United India's decision, policy terms, survey findings and current workshop/network eligibility. Consequential engine damage may raise separate cover questions, and an add-on has its own limits. Deductibles, depreciation, excluded items and unapproved work can remain payable, so obtain an itemised explanation before accepting the final repair scope.
Check restoration beyond a dry-looking cabin
After approved work, relevant engine, electrical and interior checks should be completed by appropriately qualified personnel. A dry carpet or a dashboard without a warning at one moment does not alone establish that exposure has been resolved. Retain diagnostic and specialist records where applicable, along with completion evidence requested by the insurer. Review customer-payable charges and keep receipts and final repair documents. Ask about follow-up signs such as odour, abnormal running or intermittent electrical faults. Damage assessment and correct parts supply determine timing; rapid claim registration cannot guarantee rapid restoration.
Arrange a waterlogging enquiry with CarTech Hub
Use online booking to request assessment, clearly stating water exposure. Send an insurance assistance enquiry, call or WhatsApp for scope and recovery discussion. The Seltos service article covers ordinary maintenance separately. Our Google Reviews page provides the configured feedback destination. Customers in Guwahati and Assam should confirm both insurer authorization and safe workshop capability before arranging a water-affected vehicle's repair.
Quick answers
How can a parked-vehicle water-exposure timeline be documented?
Record when the vehicle was last seen dry and when water exposure was discovered. Retain available lawful photographs, messages or CCTV references without inventing an exact exposure duration that nobody observed.
What should be agreed before removing personal items from a wet cabin?
Prioritise safety and ask which condition photographs or inventory the insurer needs. Record items handled and protect private papers appropriately; do not assume that personal belongings are covered by the vehicle repair policy.
Who approves a diagnostic charge if United India has not yet accepted the repair?
Ask for the proposed diagnostic scope and cost and clarify whether you are giving separate customer consent. Seek insurer guidance on admissibility; arranging assessment does not automatically make every diagnostic expense payable by insurance.
What helps track a warning that appears intermittently after restoration?
Keep the repair reference and note the warning, conditions and date when it occurs. Contact the repairer for review without deliberately reproducing an unsafe symptom; a record of observations is more useful than repeatedly clearing the display.